Financial statements are one of the few corporate documents in which the raw figures reveal the true story of a business. How profitable is the company? Is it able to meet its obligations? What resources does it have, and how effectively does it manage them? Foreign investors, banks, auditors, and international partners seek answers to these questions before deciding whether to enter into a partnership.
For Ukrainian enterprises operating in international markets, translating financial statements into English is becoming a vital tool for business communication. This is not simply a matter of replacing Ukrainian words with their English equivalents. It is essential to preserve the economic meaning of each indicator, the accuracy of the accounting terminology and the logic of the document.
For example, the terms ‘income’, ‘turnover’ and ‘profit’ are sometimes used almost as synonyms in everyday speech. However, in financial reporting, the English terms ‘revenue’, ‘income’ and ‘profit’ have specific meanings that depend on the context. A poor translation can create a misleading impression of a company’s financial results, even if all the figures have been transcribed without error.
Professional financial translation requires an understanding of accounting concepts, applicable accounting standards and the purpose of the documents. Its main objective is to ensure that a foreign recipient can analyze the financial information without linguistic inaccuracies or additional assumptions.
2. When a business needs its financial statements translated into English
The need to translate financial documents arises far more frequently than one might think. And not just for large international corporations. Even a small Ukrainian business planning to secure funding abroad or enter into a contract with a foreign client may be required to provide financial statements in English.
The most common situations involve investment, lending, and assessing a business’s financial soundness.
Attracting foreign investment. A potential investor assesses not only the business idea's potential but also the company’s financial performance. To do this, they analyze assets, liabilities, profitability, cash flows, and trends in key indicators over previous periods. High-quality English-language financial statements allow the reader to focus on the information without wasting time clarifying terminology.
International lending. Foreign banks and financial institutions may request balance sheets, profit and loss accounts, cash flow statements and audit reports. These documents are used to assess the borrower’s financial stability and their ability to service their debt obligations.
International tenders and grant programs. To participate in certain tenders, a company must demonstrate its financial capacity to fulfill the prospective contract. Organizers may require financial statements for one or more previous years, sometimes accompanied by an independent auditor’s report.
Due Diligence. Before entering into significant contracts, foreign partners often investigate a company’s financial position. This is particularly relevant when acquiring a business, setting up joint ventures or entering into long-term cooperation.
Other reasons may include opening a foreign bank account, registering a subsidiary, or preparing consolidated financial statements for an international group.
The list of documents will vary from situation to situation. For one recipient, a balance sheet for the last financial year may suffice, whilst another may require a full set including notes and an auditor’s report. Therefore, before commissioning a translation, it is advisable to clarify not only the list of documents but also the formatting requirements.
3. Which financial documents are translated most frequently
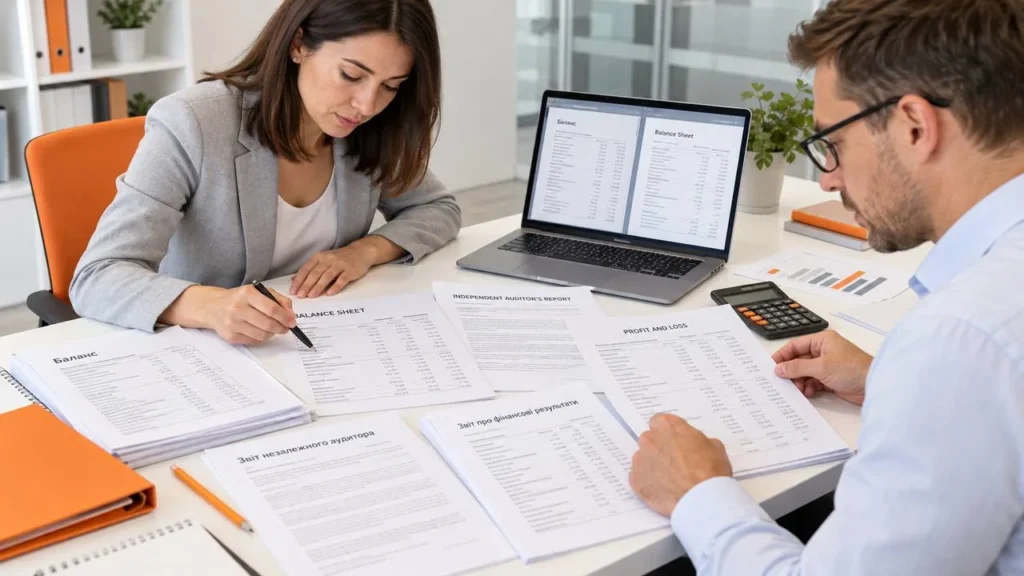
A company’s financial statements constitute a system of interrelated documents. Each one highlights a specific aspect of business activity, and together they form an overall picture of the company’s financial position.
Balance Sheet (Statement of Financial Position). This shows a company’s assets, liabilities and equity as at a specific date. This document allows an assessment of the structure of the company’s resources and the sources of their funding.
Profit and Loss Account (Income Statement / Statement of Profit or Loss). This outlines the revenue, expenses and financial results of operations for the reporting period. It is here that one can trace how sales revenue is converted into profit or loss.
Statement of Cash Flows. This shows cash inflows and outflows from operating, investing and financing activities. It is particularly important for assessing a company’s liquidity. After all, a profitable company does not necessarily have sufficient funds to meet its obligations on time.
Statement of Changes in Equity. This discloses changes in equity during the reporting period, including contributions from owners, profit distribution and the creation of reserves.
Notes to the Financial Statements. These contain explanations of accounting policies, methods of asset valuation, financial risks and other material circumstances. Sometimes it is the notes that enable one to understand the reasons behind changes in financial indicators.
Independent Auditor’s Report. This contains the auditor’s opinion on the financial statements and the explanations required by auditing standards.
In addition to the main forms, companies may require translations of trial balances, management financial reports, accounting statements and explanatory notes.
The complexity of working with such documents lies in their interdependence. For example, profit figures affect individual components of equity, whilst cash flow information complements the balance sheet data.
Therefore, when translating a complete set of financial statements, it is important to use consistent terminology, preserve the structure of the documents and correctly reproduce the cross-references between the financial statements.
4. Translation of the balance sheet: assets, liabilities and equity
The balance sheet is often the first document a foreign partner uses to assess a company’s financial position. It provides an insight not only into the total value of assets, but also into the structure of liabilities, the ratio of equity to borrowed capital, and the volume of current assets.
At first glance, translating a balance sheet should not pose any particular difficulties: standardized tables, clearly defined lines, and predominantly numerical information. However, it is precisely this apparent simplicity that often creates the false impression that the document can be translated automatically without specialist review.
The balance sheet is based on three categories:
- Assets — the company’s assets;
- Liabilities — the company’s liabilities;
- Equity — the company’s equity.
Their interrelationship is reflected in the accounting equation: Assets = Liabilities + Equity.
However, the real complexity lies in the individual line items. For example, ‘Accounts Receivable’ refers to amounts owed to the company, whilst ‘Accounts Payable’ refers to amounts owed by the company. The terms ‘Current Assets’ and ‘Non-current Assets’ are used to distinguish between current and non-current assets.
Particular care must be taken when translating articles relating to provisions, reserves, deferred tax assets and liabilities. In English-language financial practice, these terms have specific meanings that do not always align with their everyday meanings.
Another important detail is units of measurement. If figures are given in thousands of hryvnias, the English-language document must include the appropriate notation, for example ‘UAH thousand’. Otherwise, a figure representing millions of hryvnias may be mistakenly interpreted as a significantly smaller amount.
At the same time, the translator must retain the classification of items as set out in the original. The translation must not alter the financial structure of the document on its own initiative or give the impression that the accounts have been prepared in accordance with standards which the company did not in fact apply.
5. Translating the profit and loss account: how to avoid distorting financial results
Whilst the balance sheet answers the questions of what the company owns and what liabilities it has, the profit and loss account shows the results of its operations over a specific period.
For a foreign investor, this document is often one of the most interesting. It is here that one can track trends in revenue, expenses, and profit, assess the effectiveness of the business model, and identify changes in financial results.
When translating the statement, it is important to distinguish correctly between the key indicators.
‘Revenue’ refers to sales revenue, whilst ‘Gross Profit’ is the gross profit calculated after deducting the cost of sales. ‘Operating Profit’ characterizes the operating financial result, and ‘Profit Before Tax’ is the profit before taxation.
Net Profit or Net Income — the company’s net profit — is used separately.
Confusing these categories can significantly affect the perception of the company’s performance. For example, if revenue is mistakenly referred to as net profit, a foreign recipient may gain an inaccurate impression of the business’s profitability.
In IFRS reporting, the concept of ‘Other Comprehensive Income’ requires particular attention. It relates to items specified by the standards that are recognized outside profit or loss for the reporting period.
Certain challenges also arise when translating management reports. For example, the EBITDA metric is widely used to analyze operating performance, but it cannot automatically be equated with operating profit.
A high-quality translation of the profit and loss account must ensure not only the accuracy of individual terms but also the logical consistency of all financial information. This enables a foreign specialist to analyze the company’s performance using the same data presented in the Ukrainian original.
6. Translation of the auditor’s report and the independent auditor’s report
The auditor’s report holds a special status amongst financial documents. It contains the professional opinion of an independent auditor regarding the company’s financial statements in accordance with applicable standards.
For a foreign bank or investor, it is not simply the fact that an audit has been carried out that is important. What matters is the nature of the opinion expressed, the presence of any qualifications, and the circumstances the auditor considers material.
International auditing standards distinguish between several types of audit opinion.
Unmodified Opinion — an unmodified opinion. The auditor concludes that the financial statements have been prepared, in all material respects, in accordance with the applicable conceptual framework.
Qualified Opinion — a qualified opinion. This is used in circumstances specified by the standards, where the material effect of misstatements, or the potential effect of undetected misstatements, is not pervasive.
Adverse Opinion — an adverse opinion. This means the identified misstatements are material and pervasive.
Disclaimer of Opinion — a refusal to express an opinion. This may be applied when the auditor has been unable to obtain sufficient and appropriate evidence, and the possible effect of undetected misstatements may be material and pervasive.
These terms must not be replaced with approximate equivalents. For example, a disclaimer of opinion does not mean the same thing as an adverse audit opinion.
The terms ‘Key Audit Matters’, ‘Material Misstatement’ and ‘Going Concern’ require particular attention.
When translating, it is also essential to accurately reproduce the description of the responsibilities of management and the auditor, the basis for the opinion, and references to the notes to the financial statements.
It should be understood that the translation of an audit report is not a repeat audit and does not confirm the accuracy of the financial figures. The translator’s task is to convey the professional content of the conclusions without altering their meaning.
7. IFRS, NAS and international financial terminology: what a translator needs to know
Financial terminology does not exist in isolation from accounting standards. The names of financial figures, the methods of their presentation, and the structure of the financial statements depend on the rules the entity uses to maintain its accounts.
In Ukraine, the National Accounting Regulations (Standards) — NAP(S) — are used, whilst the application of International Financial Reporting Standards (IFRS) is required for certain categories of companies.
Differences between these systems may relate to the classification of assets and liabilities, valuation methods, the recognition of income and expenses, and the disclosure of information in the notes.
This is precisely why a professional translator must be familiar with the terminology of the applicable standards.
For example, the Ukrainian term ‘fixed assets’ corresponds to ‘Property, Plant and Equipment’ in the relevant context. For trade receivables, the terms ‘Trade Receivables’ or ‘Other Receivables’ may be used, depending on the nature of the item.
Particular attention should also be paid to changes in international standards. In particular, IFRS 18 Presentation and Disclosure in Financial Statements replaces IAS 1 for annual reporting periods beginning on or after 1 January 2027, with the option of early adoption. The new standard introduces changes to the presentation of financial results and the disclosure of certain items.
This illustrates why financial terminology requires constant professional updating. The translation of documents covering different reporting periods must take into account the standards that were in force at the time of their preparation.
A separate issue is the differences between IFRS and US GAAP. Despite the presence of many similar terms, these systems are not identical. Therefore, the translator must continue to be guided by the content of the original and the reporting framework under which it was prepared.
It is also important to distinguish between translation and accounting restatement. An English-language version of financial statements prepared in accordance with NAP(S)BO does not automatically become financial statements in accordance with IFRS. Such a transition may require separate work by accounting and financial specialists.
8. Common errors in the translation of financial statements and their consequences
Financial documents have one distinctive feature: even a minor error can alter the interpretation of a key indicator. However, the problems are not always linked to obvious linguistic inaccuracies.
Incorrect use of accounting terms. For example, ‘Liabilities’ refers to obligations, whilst ‘Expenses’ refers to expenditure. Both concepts relate to a company’s finances but represent different economic categories.
Errors in numerical figures. Decimal separators, spaces, currencies and units of measurement may vary depending on the language of the document. The Ukrainian notation 1 250,50 is often rendered as 1,250.50 in English. Incorrect transcription of a number can significantly alter its value.
Loss of structure in financial tables. A missing row, an incorrect heading, or a misaligned figure can disrupt the relationship between items in the financial statements. This is particularly problematic for documents containing comparative data spanning several years.
Incorrect rendering of audit qualifications. Certain phrases have established professional meanings. Inaccurate rendering of these may misrepresent the auditor’s conclusions.
Inconsistency in terminology. When the balance sheet, profit and loss account and notes are translated separately without a consistent approach to terminology, identical figures may be given different names.
The consequences of such errors depend on the purpose of the documents. Sometimes it is sufficient to make corrections. In other cases, this may result in additional inquiries from the bank, delays in the consideration of funding applications, or the need to resubmit the financial statements.
To minimize risks, financial translations require a thorough check of: terminology, numerical data, table structure, reporting periods, and cross-references.
9. Requirements for the formatting and certification of financial document translations
A high-quality translation is just one component of preparing financial documentation for use abroad. It is equally important to determine the exact format in which the documents must be submitted.
For internal analysis, negotiations with potential investors or preliminary checks on counterparties, a professional translation in electronic format is often sufficient.
At the same time, banks, government bodies and other institutions may require additional certification.
Certification by a translation agency involves the translation being issued with the relevant confirmation from the translation company. Whether this format is acceptable depends on the recipient’s requirements.
Notarisation of the translator’s signature may be required when submitting documents officially. However, the notary does not verify the accuracy of financial calculations or the authenticity of accounting information.
In some countries, certain procedures require a translation to be carried out by a sworn translator or another authorized translator. Ukrainian notarial certification does not always serve as a substitute for this format.
A separate issue concerns the apostille and consular legalization. These procedures relate to confirming the origin of the relevant official documents, but do not certify the accuracy of their content. Furthermore, not every corporate financial document can be apostilled directly.
That is why, before starting work, it is worth clarifying the destination country, the list of documents, the translation requirements, and the certification method.
Agreeing these details in advance helps to avoid unnecessary costs and situations where a completed translation has to be redone.
10. Professional translation of financial statements at the ‘STATUS KO’ Translation Center
Financial documentation is not a case where obtaining an English-language text is sufficient. The translation must accurately reflect the economic meaning of the figures, preserve the structure of the document and be comprehensible to specialists working with international financial statements.
The ‘STATUS KO’ Translation Center provides professional translation services for balance sheets, profit and loss accounts, audit reports, notes and other financial documents.
We understand that such materials require a particularly careful approach. The correct use of terminology, the accuracy of numerical figures, the preservation of tables and the consistency of information across different documents are all of paramount importance.
Work on an order begins with reviewing the materials and determining the requirements for the final translation. If the documentation is intended for a foreign bank, investor, or international organization, it is advisable to agree on the format of its presentation in advance.
We pay particular attention to the confidentiality of financial information and the responsible handling of clients’ documents.
Remote ordering is available for clients from Ukraine and other countries. Documents can be sent electronically, and the method of receiving the finished translation can be agreed on an individual basis.
Order a translation of your financial statements into English.
Are you preparing documents for a foreign bank, an international tender, an investment project or cooperation with overseas partners?
Send your financial statements to the ‘STATUS KO’ Translation Center. We will review the documents, clarify the requirements for translation and certification, and determine the cost and turnaround time.
A professionally prepared translation will help present your company’s financial information clearly, accurately and in a format suitable for international business communication.
11. FAQ — Frequently asked questions about the translation of financial statements into English
1. How much does it cost to translate financial statements into English?
The cost is determined by the volume of material, the complexity of the accounting terminology, the number of tables, the turnaround time, and whether certification is required. For example, translating a standalone balance sheet and a full annual report with notes requires a different amount of work. For an accurate quote, please send the documents for a preliminary assessment.
2. How long does it take to translate a balance sheet or annual financial statements?
Turnaround times depend on the volume and complexity of the documentation. Translating a full set of annual accounts, including audit materials, usually takes longer than translating a single balance sheet. The possibility of an urgent turnaround is assessed on a case-by-case basis.
3. Can I commission a translation of financial statements prepared in accordance with IFRS?
Yes. Translating IFRS financial statements requires the use of appropriate international accounting terminology. It is important to take into account the standards under which the document was prepared and not to confuse translation with the accounting restatement of financial statements.
4. How does the translation of a balance sheet differ from that of a profit and loss account?
The balance sheet reflects a company’s financial position as at a specific date, whilst the profit and loss account sets out the results of operations for a specific period. Accordingly, these documents contain different financial categories and require different terminological approaches.
5. Does a translation of financial statements need to be notarised?
Not always. For internal analysis or preliminary negotiations, a professional translation without notarisation is often sufficient. If the documents are to be submitted to an official body, the requirements must be clarified directly with the recipient.
6. Can financial statements be translated using artificial intelligence?
Automated tools can assist with text processing, but they do not guarantee the correct use of specialized terminology or the accuracy of financial phrasing. Professional proofreading is essential for important documents. The risks of entrusting confidential information to third-party services should also be considered.
7. Do all notes to the financial statements need to be translated?
If the recipient requires a full set of financial statements, the notes usually need to be translated as well. They contain explanations of accounting policies, the structure of financial figures and financial risks. Without them, certain data may be unclear.
8. Does the auditor’s report need to be translated along with the financial statements?
This depends on the requirements of the organization to which the documents are being submitted. In the context of international lending, investment due diligence or participation in certain tenders, the auditor’s report may be a mandatory part of the submission.
9. Can I order a translation of financial statements remotely whilst abroad?
Yes. The ‘STATUS KO’ Translation Center accepts orders remotely. Documents can be sent electronically, and the method of receiving the finished translation can be agreed upon when placing the order.
10. What documents do I need to provide to get a quote for the translation of financial statements?
For a preliminary quote, you will need to provide the documents to be translated, specify the destination country, your preferred turnaround time, and indicate whether certification is required. Based on this information, we can determine the scope of work and prepare a personalized quote.